Every year, counties across the country sell the right to collect unpaid property taxes, and most investors have no idea the market exists. Tax lien investing lets you earn a government-set interest rate secured by real property, often without ever owning a house. At Real Estate Sales LLC, we walk investors through how these sales work so they can decide whether the returns fit their strategy.
How Unpaid Taxes Become an Investment
When an owner stops paying property taxes, the county still needs revenue. Rather than wait, it sells either a lien against the property or the deed itself at public auction. You pay the delinquent taxes, and in exchange you receive either the right to collect that amount plus interest, or ownership outright, depending on the state.
Tax Liens Versus Tax Deeds
This distinction decides your whole strategy. In lien states you buy a claim and collect interest when the owner redeems, typically within one to three years. In deed states you buy the property itself at auction. A handful of states use hybrid systems. Know which one governs your target county before you bid a single dollar.
The Returns and Who Sets Them
Interest rates are set by statute, not by the market, and commonly range from eight to eighteen percent annually depending on the state. In competitive counties, bidders drive the effective yield down by bidding the rate lower or paying a premium. The advertised rate is a ceiling you rarely capture in a crowded auction.
Doing Your Homework Before the Sale
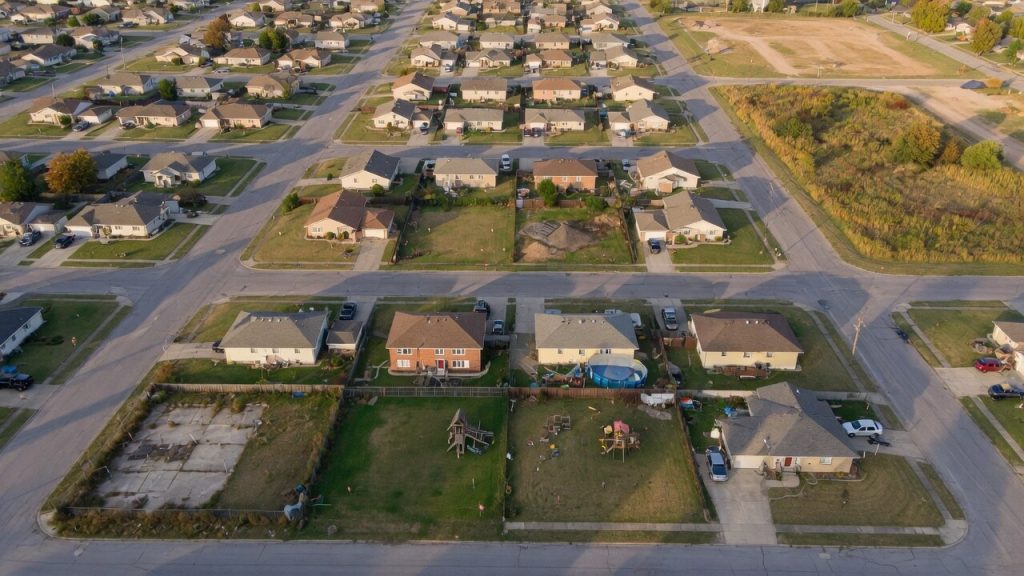
Never bid on a parcel number alone. Pull the assessment, look at the property on a map, and drive it if you can. Liens on landlocked strips, contaminated lots, and condemned structures are common traps. If the owner never redeems and you end up with the deed, you want a property you would actually be willing to own.
Redemption Periods and Foreclosure
Most liens are redeemed, which is the outcome you should expect and underwrite for. If the owner does not pay within the redemption window, you must follow a formal foreclosure process to take title, and that requires legal work and notice to every interested party. Budget for attorney fees before you assume a windfall.
The Risks Nobody Advertises
Your capital is illiquid, sometimes for years, and it earns nothing extra for waiting. Subsequent-year taxes may need to be paid to protect your position. Municipal liens, IRS claims with redemption rights, and bankruptcy filings can all complicate collection. Treat this as a fixed-income allocation, not a shortcut to owning cheap houses.
Build Your Investing Strategy the Right Way
At Real Estate Sales LLC, our Flip Cheap Houses™ program helps you decide where tax lien investing fits alongside flipping and rentals, so your capital goes where it earns the most.
Visit FlipCheapHouses.com to learn how to put your capital to work in real estate!